Nigeria’s FX Recovery: Has Stability Become Credibility?
Nigeria has moved from conditional FX stability into substantive market normalization. What remains conditional is the durability, depth and accessibility of that stability under stress.
What federal friction is—and is not—changing for capital, energy and long-duration decisions
Canada's federal bargain is being tested in Alberta.
The immediate political focus is a referendum. For capital, however, the more consequential question is not simply what Albertans may decide at the ballot box. It is whether constitutional uncertainty is beginning to change the assumptions on which investors, lenders, infrastructure developers and businesses make long-duration decisions.
The evidence requires precision.
Some decisions are already being affected. Constitutional uncertainty has entered investor diligence, business expansion planning and, historically, at least one major-project final-investment decision.
But the evidence does not support a generalized Alberta investment retreat. Major capital commitments continue. Most surveyed Alberta CEOs still intend to maintain or increase investment. Long-duration infrastructure arrangements continue to advance. Alberta's reported sovereign-credit outlooks remain stable.
That creates an institutional condition more complex than either political reassurance or separation alarmism captures.
Constitutional uncertainty has entered some decision rooms. It has not demonstrably entered the general price of Alberta capital.
PRIPEX therefore classifies the T0 Capital Threshold as:
LOCALIZED
The distinction matters because political friction can become economically consequential well before it becomes a generalized financial risk premium.
Table of contents [Show]
The referendum is politically consequential, but investors should resist treating the ballot itself as a binary proxy for Alberta's future institutional configuration.
A referendum can alter expectations without immediately altering jurisdiction.
Between a political signal and a changed investment environment lie multiple institutional interfaces: constitutional law, federal-provincial negotiation, energy and infrastructure arrangements, Indigenous and treaty rights, fiscal architecture, trade and market access, regulation, financing and implementation.
Capital therefore faces a different question from the electorate.
The investor question is not simply:
What will the referendum say?
It is:
Which assumptions supporting a particular investment could become conditional if the institutional relationship changes?
That is the point at which constitutional politics becomes investment intelligence.
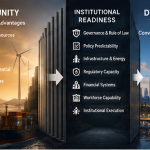
The referendum environment creates multiple political and constitutional questions, but for PRIPEX they collapse into one institutional stress test:
Are consequential capital or resource decisions beginning to depend on assumptions that constitutional uncertainty has made less dependable?
That test prevents political intensity from being mistaken for financial causality.
The relevant evidence is behavioural.
At T0, those questions do not produce one uniform answer.
The evidence reaches some of the early stages of that sequence. It does not reach the later ones.
Three forms of decision-level evidence establish that the issue has moved beyond political rhetoric.
First, constitutional uncertainty has previously entered a major-project FID decision.
ATCO disclosed in 2025 that foreign partners in an Alberta hydrogen project withheld final investment commitment while seeking greater certainty around issues including market access, currency and trade arrangements.
That is important mechanism evidence: constitutional uncertainty can become sufficiently material to alter a major project's decision conditions.
But its date is equally important.
The disclosure predates the current October 2026 referendum. It is therefore historical mechanism evidence, not evidence that the present referendum caused that FID decision.
Second, current expansion and location planning has changed for some businesses.
A Calgary Chamber survey of 137 members found that 19% reported slowing Alberta expansion plans and 15% reported actively examining relocation. These are reported changes to business planning rather than abstract perceptions.
The limitations remain significant: the public evidence does not establish associated capital amounts, completed relocations or independently verified transactions.
Third, referendum uncertainty has entered investor diligence.
A prospective U.S. investor raised the referendum directly during investment discussions with Calgary fintech Helcim.
That demonstrates a change in the questions being asked by prospective capital. It does not establish a changed valuation, financing term, hurdle rate or ultimate investment decision.
The distinction is fundamental.
An investor question is not a capital flight.
A planning contingency is not a cancelled project.
An FID condition is not necessarily financing repricing.
But each can be an earlier stage in the transmission of institutional uncertainty into capital decisions.
The counter-evidence is substantial.
The Business Council of Alberta's CEO evidence, gathered while the referendum environment was already known, showed 55% planning increased capital investment, 42% maintaining investment and only 3% planning reductions. Half planned additional hiring. Regulation—not the referendum—was identified as the leading growth barrier.
Major capital is also continuing to enter Alberta.
Meta committed more than C$13 billion to its Sturgeon County data-centre project, with construction underway. Capital Power subsequently reported continuing discussions with additional data-centre proponents.
Long-duration infrastructure architecture has continued as well. Canada, Alberta and private-sector participants have continued advancing arrangements involving pipeline development, carbon capture and storage, financing and Indigenous equity participation.
Alberta's reported sovereign-credit assessments also retained stable outlooks or trends at the T0 cut-off.
None of this proves constitutional uncertainty has zero private cost.
Private credit memoranda, investment-committee papers, insurer files and corporate hurdle-rate decisions are generally inaccessible.
But the observable counter-evidence matters.
It prevents isolated decision effects from being transformed into an unsupported claim of generalized capital repricing.
This is the central institutional contradiction at T0:
Political and institutional friction can coexist with functioning federal accommodation.
Both conditions are observable simultaneously.
For long-duration capital, the referendum matters through interfaces rather than headlines.
Political decisions must pass through Canada's constitutional architecture before they become changed jurisdictional conditions.
That creates sequencing risk. Investors may need to distinguish political mandate, legal authority, negotiation, implementation and eventual operating consequences rather than treating them as one event.
Long-duration investment depends on assumptions about taxation, public finance, currency, sovereign and sub-sovereign credit, transfers, regulation and market access.
The T0 evidence does not establish systemic repricing across those channels.
It does establish that questions about some of them can enter project decision-making.
Alberta's investment proposition is deeply connected to energy, electricity, pipelines, carbon management, transportation and export infrastructure.
These systems frequently cross jurisdictional boundaries and depend on multiple public and private actors.
The continued advancement of long-duration infrastructure during the referendum period is therefore material counter-evidence to a thesis of institutional paralysis.
Constitutional change cannot be analysed as a federal-provincial bilateral matter alone.
First Nations have already committed legal and institutional resources in response to separation-related processes, while major-project Indigenous equity architecture continues.
The T0 evidence demonstrates institutional response. It does not demonstrate referendum-specific deterioration in Indigenous project-finance terms or investment commitments.
This is where institutional uncertainty becomes measurable for PRIPEX.
The relevant indicators are not the volume of political argument but changes to diligence, optionality, FID conditions, transaction structures, financing terms and ultimately pricing.
At T0, evidence exists at some early and intermediate stages of that transmission mechanism.
It does not extend across the full chain.
PRIPEX uses a progression to distinguish political noise from financially consequential institutional change:
Political issue → investor question → planning optionality → FID condition → transaction restructuring → financing repricing → jurisdiction-wide risk premium
Alberta has moved beyond the first stage.
Investor questioning is demonstrated.
Planning optionality is demonstrated among selected businesses.
Historical evidence demonstrates that constitutional uncertainty can become an FID condition for a major Alberta project.
But the available evidence does not establish referendum-driven transaction restructuring at scale, generalized financing repricing or a jurisdiction-wide risk premium.
Accordingly:
Capital Threshold: LOCALIZED
This is stronger than saying no capital effect has been demonstrated.
It is materially weaker than saying Alberta capital has been generally repriced.
The most defensible T0 formulation is:
Alberta's constitutional friction has crossed the Capital Threshold locally: it has entered investor diligence, delayed at least one documented major-project FID historically, and changed expansion/location planning for some current businesses. It has not crossed into demonstrated generalized repricing of Alberta capital.
Or more simply:
Constitutional uncertainty has entered some decision rooms. It has not demonstrably entered the general price of Alberta capital.
The T0 evidence does not justify forecasting which constitutional path Alberta will take.
It does, however, establish four decision environments that capital should distinguish.
Political disagreement remains elevated, but existing institutional arrangements continue absorbing it without materially changing the assumptions underlying most investment decisions.
In this trajectory, monitoring remains important, but constitutional uncertainty does not progress materially along the Capital Threshold.
Federal, provincial, industry and Indigenous actors continue reaching arrangements that preserve or clarify enough of the operating environment for long-duration decisions to proceed.
The evidence that major investment and infrastructure arrangements continue during political friction demonstrates that accommodation and disagreement are not mutually exclusive.
Uncertainty persists long enough, or becomes specific enough, that additional investors begin introducing constitutional conditions into diligence, planning, FID or transaction structures.
This would move the observable evidence further along the Capital Threshold without necessarily producing generalized repricing.
Institutional change becomes sufficiently concrete that assumptions concerning market access, fiscal arrangements, regulation, currency, financing, treaty relationships or infrastructure governance require substantive redesign.
T0 evidence does not establish this trajectory.
It remains a monitoring architecture, not a forecast.
The same constitutional signal does not carry equal weight for every decision-maker.
Long-duration infrastructure sponsors are exposed to regulatory, market-access and intergovernmental assumptions extending over decades.
Energy and resource investors may depend on export routes, carbon architecture, permitting, electricity systems and federal-provincial coordination.
Foreign direct investors may require clarity on jurisdiction, trade, currency, tax, market access and dispute architecture before committing irreversible capital.
Lenders and project-finance participants become particularly important if constitutional uncertainty begins altering spreads, covenants, tenor, security requirements or underwriting assumptions. T0 does not demonstrate that generalized transition.
Corporate boards considering expansion or location decisions can respond earlier because planning optionality itself has value.
Indigenous governments and investment entities operate within treaty, consultation, ownership and financing architectures that cannot be reduced to federal-provincial politics.
Data-centre and power-intensive investors provide an important counter-test: major investment continues despite the referendum environment.
The practical implication is not that Alberta has become generically riskier.
It is that constitutional sensitivity varies by decision architecture.
The T0 classification is evidence-dependent.
Evidence capable of moving the assessment would include observable changes in:
The absence of public evidence in these areas is not proof that private effects do not exist.
It is a boundary on what can responsibly be claimed.
That boundary remains part of the intelligence.
Alberta's referendum is testing Canada's institutional bargain, but the capital consequences are not adequately described by either complacency or alarm.
The evidence supports a narrower conclusion.
Selected businesses have altered planning.
A prospective foreign investor has introduced the referendum into diligence.
Historical evidence demonstrates that Alberta constitutional uncertainty can become an FID condition.
At the same time, substantial investment continues, CEO capital intentions remain predominantly stable or expansionary, infrastructure arrangements continue to advance and reported provincial credit outlooks remain stable.
The resulting institutional signal is therefore neither “nothing has changed” nor “Alberta capital is being repriced.”
It is:
Alberta's constitutional friction has become consequential for selected capital and business decisions, but it has not become demonstrated generalized repricing of Alberta capital.
For investors, executives and institutions, the immediate task is not to predict a constitutional outcome.
It is to identify which assumptions their decisions depend upon, which of those assumptions have become conditional, and what observable evidence would justify changing position.
That is the distinction between reacting to political uncertainty and positioning for institutional change.
Not Prediction. Positioning.
Global News — ATCO CEO / Alberta separatism and hydrogen-project FID: globalnews.ca/news/11180647/alberta-separatism-atco-ceo/
Global News — Calgary Chamber survey / expansion and relocation planning: globalnews.ca/news/11936367/calgary-chamber-of-commerce-separation-impact/
CityNews Calgary — Helcim / prospective U.S. investor referendum diligence: calgary.citynews.ca/2026/05/22/alberta-separation-canadian-chamber-of-commerce/
Business Council of Alberta — CEO Pulse Survey, Summer 2026: businesscouncilab.com/reports/alberta-ceo-pulse-survey-summer-2026/
Meta Data Centers — Sturgeon County investment: datacenters.atmeta.com/2026/07/hello-sturgeon-county/
Reuters — Capital Power / Alberta hyperscaler pipeline, 21 September 2026.
Government of Alberta — Investor Relations / provincial credit ratings.
Government of Canada — Canada–Alberta energy/infrastructure framework, July 2026.
Siksika Nation — separation-referendum petition court challenge.
Alberta Chambers — referendum/business-perception research.
Comparative historical research in the T0-V evidence record — contextual only; not used as proof of current Alberta capital behaviour.
PRIPEX Intelligence translates structural signals into decision architecture for institutions, executives and capital allocators.
Nigeria has moved from conditional FX stability into substantive market normalization. What remains conditional is the durability, depth and accessibility of that stability under stress.
Reserve adequacy is no longer just a technical balance-of-payments metric. It is becoming a market-facing signal of institutional credibility, monetary-policy flexibility, and shock-absorption capacity. PRIPEX interprets this as a structural shift: reserve strength is becoming a credibility gatekeeper for emerging-market capital access.