Alberta's Referendum Is Testing Canada's Institutional Bargain
What federal friction is—and is not—changing for capital, energy and long-duration decisions
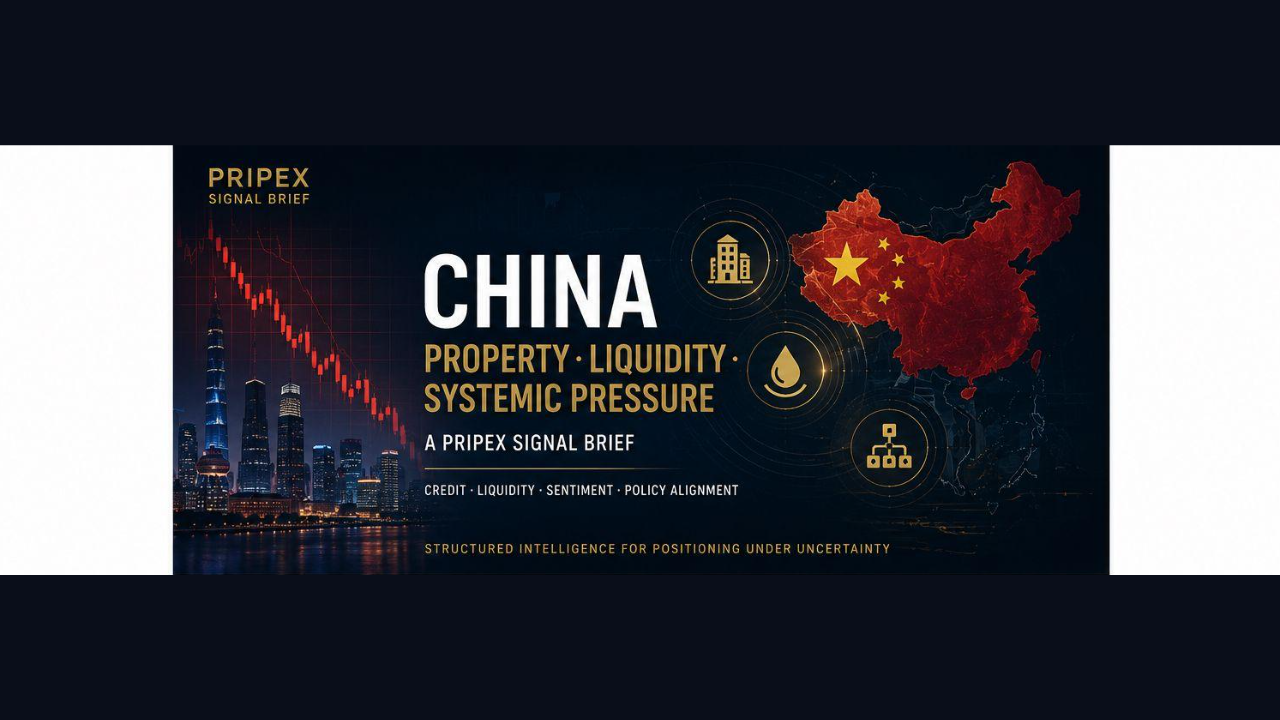
China's property-sector stress is no longer only a real estate issue. It is a systemic positioning signal affecting liquidity confidence, household balance sheets, local government finance, and global capital interpretation.
What does China's property-sector stress signal for global capital positioning?
China's property-sector stress is not a contained domestic event. It is a systemic signal affecting liquidity confidence, local government finance, household balance sheets, and global capital interpretation. Institutional positioning requires structural assessment of transmission risk, not surface-level property metrics alone.
Table of contents [Show]
China's property sector has experienced a sustained period of stress. Developer defaults, project incompletions, household confidence deterioration, and local government fiscal exposure have converged into a structural positioning challenge. For institutional actors, the significance of this stress extends well beyond the real estate sector itself.
This brief assesses the structural characteristics of China's property-sector stress, its systemic transmission channels, and the positioning implications for capital allocation decisions across sovereign, institutional, and cross-border contexts.
China's property sector historically accounted for a substantial share of household wealth, local government revenue, and fixed-asset investment. When stress in this sector becomes sustained and structural rather than cyclical, it generates second-order effects that redefine the operating environment for institutional capital.
Liquidity confidence is affected not only by developer solvency, but by the broader credibility of policy response mechanisms. Household balance sheets, significantly weighted toward property assets, experience a wealth-effect compression that affects consumption, savings behaviour, and financial system confidence. Local governments, historically reliant on land sales and related revenues, face structural fiscal challenges that affect service delivery capacity and investor confidence in subnational fiscal frameworks.
For global institutional actors, China's property-sector stress is a lens through which systemic resilience, policy capacity, and sovereign positioning signals must be re-read.
The stress in China's property sector reflects several interlocking structural dynamics:
Developer leverage and liquidity risk: High-leverage development models created exposure to refinancing risk and demand volatility. When demand moderated and credit conditions tightened, the structural fragility of leverage-dependent development models became visible.
Local government finance dependence: Local government financing vehicles and land-sale revenues created fiscal frameworks with limited buffer capacity in a sustained low-land-sale environment. This fiscal exposure is a systemic variable, not merely a sectoral one.
Household wealth concentration: Property as a dominant household wealth store creates a direct channel between property-sector conditions and household balance sheet health, affecting consumer confidence and financial system stability simultaneously.
Policy calibration complexity: The structural interdependencies between the property sector, local government finance, household balance sheets, and financial system stability make policy calibration complex. Support measures targeted at one dimension carry spillover effects in others.
China's property-sector stress affects liquidity and credit conditions through multiple transmission channels. Developer stress creates counterparty exposure for financial institutions holding developer debt and related instruments. Project incompletions affect mortgage-holder confidence and create legal and reputational exposure for banks. Local government fiscal stress affects the capacity of subnational borrowers to service obligations and maintain investment commitments.
Credit transmission effectiveness — the capacity of monetary policy to translate into real economic activity — is affected when household and corporate actors are in balance-sheet repair mode rather than expansion mode. This creates a structural constraint on monetary policy transmission that is relevant to assessments of China's policy support capacity.
Liquidity confidence — the degree to which market participants trust in the availability and predictability of liquidity under stress — is a leading signal for institutional behaviour in cross-border capital allocation contexts.
China's systemic positioning signal reaches global institutional actors through several channels:
Trade and demand effects: China's domestic demand conditions affect commodity demand, trade volumes, and growth expectations in export-oriented economies globally. Property-sector stress that affects domestic investment and consumption flows through to demand signals for global producers and exporters.
Capital flow dynamics: Shifts in investor confidence regarding China's institutional environment affect cross-border capital flows, risk appetite for regional assets, and portfolio rebalancing decisions in global institutional mandates.
Currency and reserve dynamics: China's monetary policy responses to domestic stress, including exchange rate management and reserve deployment, have direct implications for global currency markets and reserve asset positioning.
Contagion sensitivity: For emerging market and Asia-Pacific exposures, China's systemic conditions set a confidence baseline that affects regional risk appetite and institutional positioning across correlated asset classes.
Institutional actors respond to systemic stress signals through several observable patterns: enhanced due diligence on China-linked counterparty exposure; portfolio rebalancing toward lower-correlated assets; increased scrutiny of emerging market allocations with China transmission sensitivity; and re-assessment of sovereign credit and local government obligation frameworks.
What distinguishes sophisticated institutional positioning from reactive repositioning is the quality of the structural assessment framework applied. Surface-level property metrics are insufficient. Structural positioning requires assessment of liquidity confidence trajectories, policy support capacity, credit transmission conditions, and systemic containment indicators over a sustained horizon.
PRIPEX structural intelligence is designed to support this level of assessment, offering institutional actors a consistent, governed, and methodology-grounded view of systemic positioning signals across sovereign and institutional contexts.
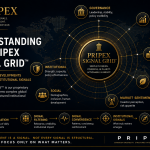
PRIPEX tracks the following indicators as part of ongoing China systemic positioning assessment:
Assessment date: May 2026. Canonical scorecard reflects PRIPEX structural assessment based on publicly available indicators and governed methodology.
| Metric | Trend | Status |
|---|---|---|
| Property Sector Stress | → flat | Fragile |
| Liquidity Confidence | → flat | Weakening |
| Credit Transmission | → flat | Weakening |
| Local Government Exposure | ↑ up | Fragile |
| Policy Support Capacity | → flat | Stable |
| Household Confidence | → flat | Weakening |
| Global Spillover Sensitivity | ↑ up | Weakening |
| Execution Capacity | → flat | Pro |
| Shock Absorption Capacity | → flat | Pro |
| Systemic Containment Strength | → flat | Pro |
Public Interpretation: China's property-sector stress remains structurally significant. Public indicators suggest fragile property conditions, uneven liquidity confidence, weak credit transmission, and elevated local-government exposure. Policy support capacity remains a stabilizing factor, but deeper assessment of execution capacity, shock absorption, and systemic containment strength is reserved for PRIPEX access products.
China's property-sector stress is a structural systemic signal, not a cyclical correction. The interlocking dynamics of developer liquidity risk, local government fiscal exposure, household balance sheet stress, and credit transmission constraints create a positioning environment that requires sustained structural monitoring rather than episodic assessment.
Policy support capacity remains a stabilizing factor. Central government fiscal and monetary tools retain meaningful deployment capacity. However, the structural complexity of the interdependencies involved — and the multi-year nature of property-sector adjustment — means that institutional actors should not interpret policy support as a resolution of underlying structural positioning risk.
Global spillover sensitivity is elevated and trending upward. For institutional actors with China-linked exposures — whether direct, trade-mediated, or through correlated emerging market positions — structural monitoring of China's liquidity confidence, credit transmission, and systemic containment indicators is a material component of responsible portfolio positioning.
PRIPEX tracks execution capacity, shock absorption capacity, and systemic containment strength as Pro-level metrics. Deeper assessment of these dimensions is available through PRIPEX access products.
Internal reference: PRIPEX Methodology | Disclaimer
PRIPEX ProAccess
For deeper PRIPEX analysis of China's property stress, liquidity confidence, and systemic containment indicators, unlock the expanded report or subscribe to PRIPEX Pro.
Unlock Full Report Access | Subscribe to PRIPEX Pro | Request Custom Intelligence Review
Disclaimer: PRIPEX content is informational and analytical in nature. It does not constitute investment advice, financial advice, legal advice, tax advice, or any form of regulated professional guidance. Users remain responsible for their own independent decisions.
What federal friction is—and is not—changing for capital, energy and long-duration decisions
Nigeria has moved from conditional FX stability into substantive market normalization. What remains conditional is the durability, depth and accessibility of that stability under stress.